Day: December 18, 2021
-
20: An Individual’s Tax Residence under S 7(1)(c) ITA 1967
An individual’s tax residence under S 7(1)(c) ITA 1967 – PDF
1. The residence test under s 7 of the Income Tax Act 1967 (ITA) is purely a quantitative one, based on the number of days an individual is present in Malaysia during a year of assessment.
2. Under s 7(1)(c) of the ITA 1967:
When a person has been in Malaysia for 90 days or more (which need not be consecutive) in a Basis Year, he is deemed to be resident for tax purposes under section 7(1)(c) of the Income Tax Act 1967 for the relevant Basis Year, if, in any three of the four preceding basis years, he satisfies the following conditions:-
👉 Condition i: has been resident under section 7(1) of the Income Tax Act 1967; or
👉 Condition ii: has stayed in Malaysia for 90 days or more.
3. In simple terms, if a person stays in Malaysia for 90 days or more, whether he is a Malaysian tax resident or not, we need to look at his whereabouts for the previous 4 years and whether he has been a resident of Malaysia or stayed in Malaysia for 90 days or more for 3 of those years.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 1967年所得税法令第7条规定的居民身份的鉴定,纯粹以定量为基础,是根据个人在一个课税年度中停留在马来西亚的天数。
2. 1967年ITA第 7(1)(c) 条文阐明: 当一个人在某个基础年 [Basis Year] 在马来西亚逗留了 90天或以上(不一定需要是连续的)的时间时,在1967年所得税法令第7(1)(c)条文下,他会被认为是有关基础年 [Basis Year] 的税务居民,如果在之前的四个基准年中的任何三年,他符合以下的条件:
👉 条件 i: 在1967年所得税法令第7(1)条文下,拥有居民身份;或
👉 条件 ii:在马来西亚逗留了90天或以上。 3. 简单来说,一个人只要在马来西亚逗留90天或以上,他究竟是不是马来西亚税务居民,我们需要看他之前4年的行踪,有没有其中3年:
👉 是马来西亚的居民;又或者
👉 在马来西亚逗留90天或以上
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
21: An Individual’s Tax Residence under S 7(1)(d) ITA 1967
An individual’s tax residence under S 7(1)(d) ITA 1967 – PDF

1. The residence test under s 7 of the Income Tax Act 1967 (ITA) is purely quantitative, based on the number of days an individual is present in Malaysia during a year of assessment.
2. Under s 7(1)(d) of the ITA 1967: an individual can be considered to be a resident of Malaysia even if he did not spend any time in Malaysia during the basis year in question.
if:
👉 Condition i: resident for the immediate following basis year; and
👉 Condition ii: have been resident for the three immediate preceding basis years.
3. As a result, when it comes to tax planning, taxpayers must exercise extreme caution.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 1967年所得税法令第7条规定的居民身份的鉴定,纯粹以定量为基础,是根据个人在一个课税年度中停留在马来西亚的天数。
2. 1967年ITA第 7(1)(d) 条文阐明:一个人在有关基准年 [Basis Year] 即使没有马来西亚有任何时间的停留,也可以被认为是马来西亚的居民,如果他
👉 条件 i: 在相关课税年的下一个基础年 [Immediate following Basis Year] ,其身份是税务居民;及
👉 条件 ii:在相关课税年的前三个基础年,已经是马来西亚的税务居民。
3. 因此,在做税务规划时,纳税人可要非常小心。
4. 下载 – https://www.ccs-co.com/publications
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
22: An Individual’s Tax Residence under S 7(1A) ITA 1967
An Individual’s Tax Residence under S 7(1A) ITA 1967 – PDF

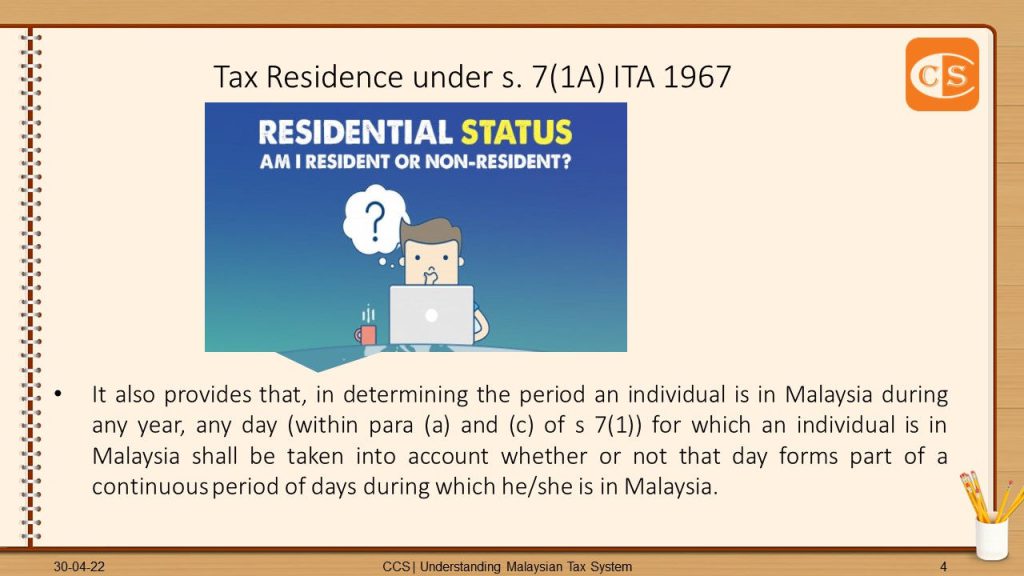
1. The residence test under s 7 of the Income Tax Act 1967 (ITA) is purely quantitative, based on the number of days an individual is present in Malaysia during a year of assessment.
2. Under paragraph 7(1A) of the ITA, when determining the residence of an individual, the individual shall be deemed to be in Malaysia for a day if the individual is present in Malaysia for part of that day.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 1967年所得税法令第7条规定的居民身份的鉴定,纯粹以定量为基础,是根据个人在一个课税年度中停留在马来西亚的天数。
2. 第7(1A)条规定,在确定一个人的税务居民身份时,如果该人在一天中有部分的时间是停留在马来西亚,那么他就应该被视为在马来西亚逗留一天。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy



-
23: Move to Tax Foreign-Sourced Income in Malaysia is not a Surprise

Over the past few years, the concept of “Double Non-Taxation” has been an issue. When the Base Erosion and Profit Shifting [BEPS] project of the Organization for Economic Cooperation and Development [OECD] was first launched, this was identified as a potential issue.
Thus, the taxation of foreign-sourced income received in Malaysia will begin on January 1, 2022, as announced during the delivery of Budget 2022.
The proposal is the government’s response to Malaysia’s recent placement on the Council of the EU’s list of jurisdictions that have committed to amending or abolishing their detrimental foreign-sourced income exemption regimes, announced on 5th October 2021.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
在过去的几年里,“双重不征税 ”的概念一直是一个问题。当经济合作与发展组织 [OECD] 的税基侵蚀和利润转移 [BEPS] 项目首次展开时,这被认为是一个潜在的问题。 因此,正如在提呈2022年预算案时宣布的那样,在马来西亚收到源自国外的收入将从2022年1月1日开始被征税。 该提案是政府对马来西亚最近被列入欧盟理事会的司法管辖区灰色名单的一项回应措施,承诺修正或废除不利的源自国外收入的豁免制度,该名单是在今年10月5日宣布的。
#税法之道博大精深,#建议大家深度学习


#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy
-
24: FAQs – Special Income Remittance Programme (PKPP)
FAQs – Special Income Remittance Programme (PKPP)

1. The Inland Revenue Board (IRB) has published Frequently Ask Questions (FAQs) about a “Special Program for the Remittance of Foreign Income” for Malaysian Tax Residents who have money kept outside of Malaysia.
2. To find out more, you may consider tonight’s Live – https://lnkd.in/g7aTtcd2
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 税收局 (IRB) 刚刚已经发布了关于 “源自国外的收入汇款特别计划 ”的常见问题解答 (FAQs)(国文版本),该计划适用于所有在马来西亚境外有资金存放的马来西亚税务居民 [Malaysian Tax Residents]。
2. 想要了解更多,今晚的 Live 锁定你 – https://lnkd.in/g7aTtcd2
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy