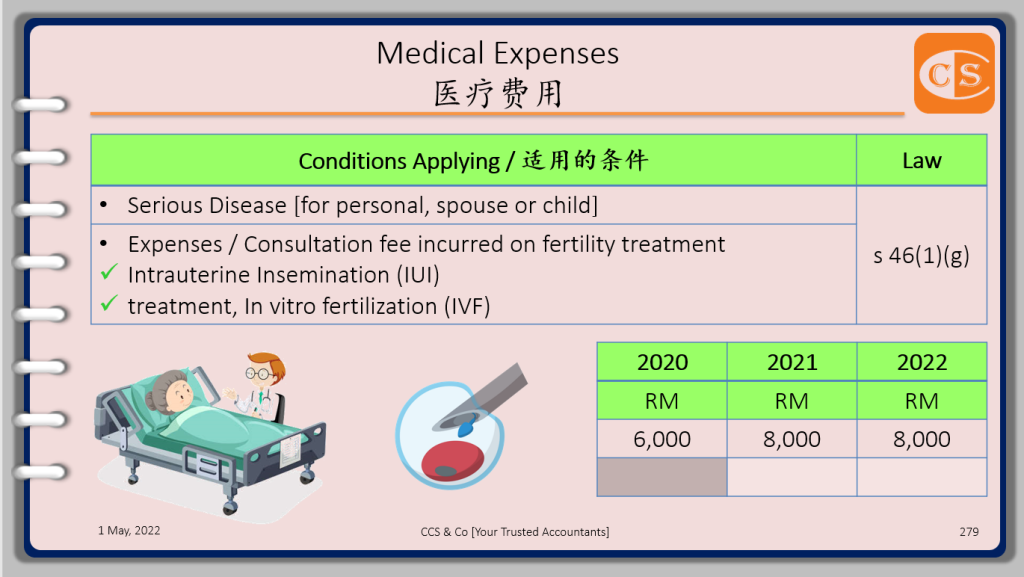
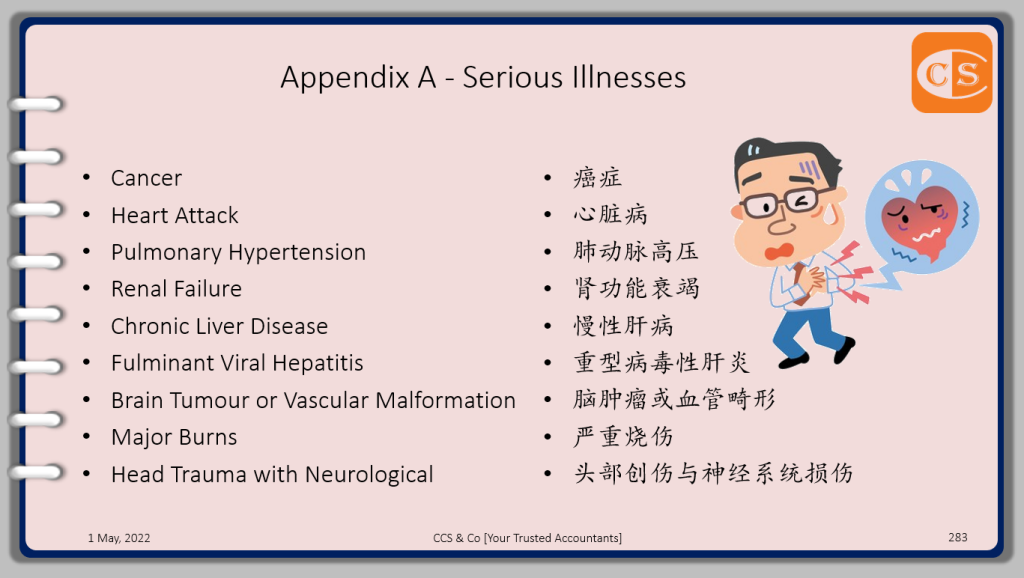
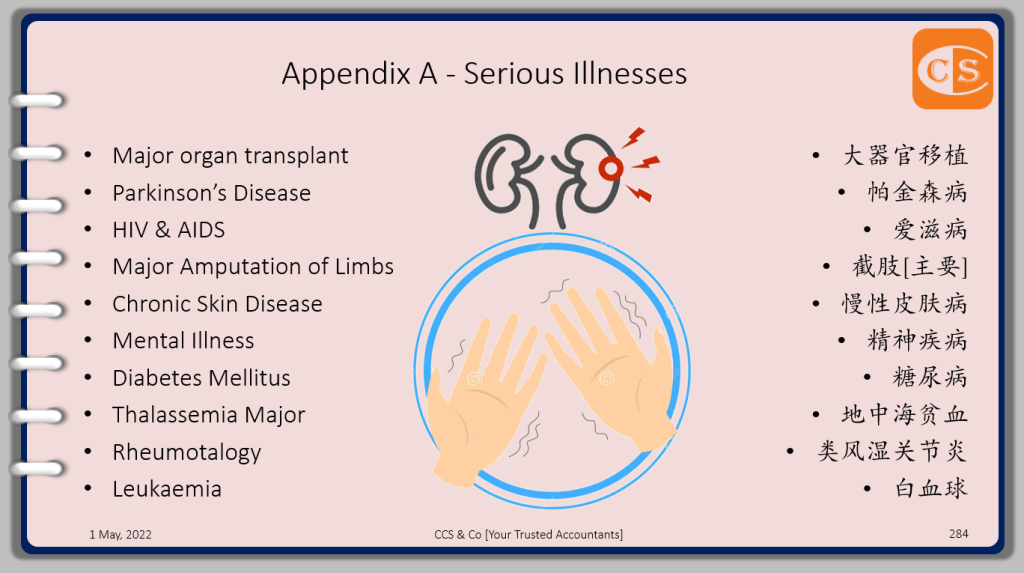
The IRB has on 4 May 2011 issued guidelines on serious diseases for the purpose of claiming relief under s 46(1)(g). A taxpayer may claim relief of not more than RM8,000 on medical expenses expended on himself/herself, his/her spouse and children for serious diseases suffered. A serious disease is defined in s 46(2) to include “acquired immunity deficiency syndrome, Parkinson’s disease, cancer, renal failure, leukemia, and other similar diseases”.
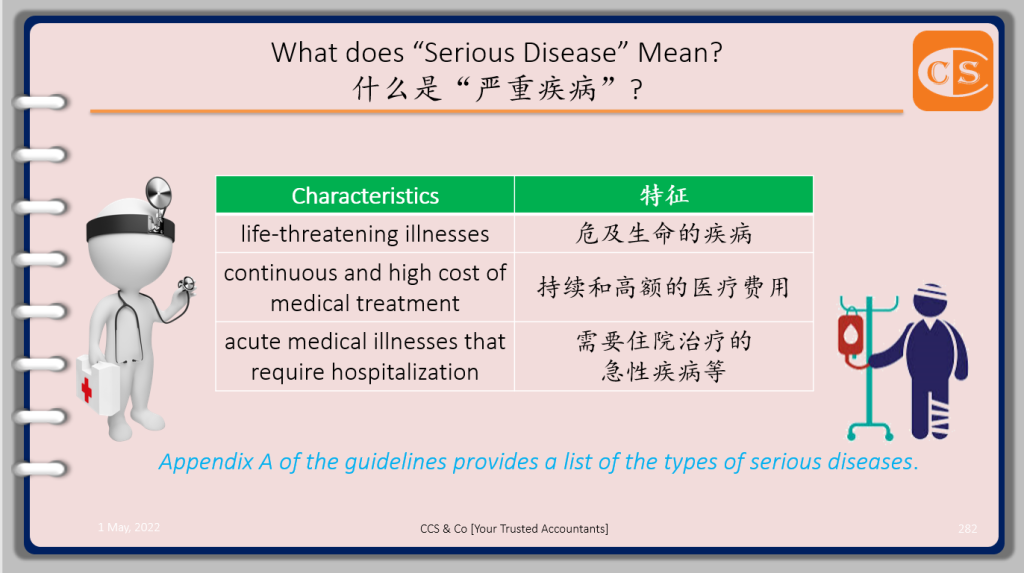
The guidelines elaborate that serious diseases are acute and chronic illnesses that cannot be cured and require prolonged medical treatment.
Some of the characteristics of serious illnesses include:
life-threatening illnesses,
continuous and high cost of medical treatment,
acute medical illnesses that require hospitalisation, etc.
Appendix A of the guidelines provides a list of the types of serious diseases.
1. The test of residence under s 7 of the Income Tax Act 1967 (ITA) is purely a quantitative one, based on the number of days an individual is present in Malaysia during a year of assessment.
2. Under s 7(1)(b) ITA 1967, when an individual is in Malaysia for less than 182 days (the shorter period), but is linked to or by a period of 182 or more consecutive days (the longer period) in the basis year immediately preceding or immediately following that particular basis year, the individual qualifies as a resident for that basis year.
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
1. The test of residence under s 7 of the Income Tax Act 1967 (ITA) is purely a quantitative one, based on the number of days an individual is present in Malaysia during a year of assessment.
2. In applying s 7(1)(b) of the ITA 1967:
👉 to identify periods of less than 182 days or more than 182 consecutive days,
👉 we also need to take into account the possibility that the taxpayer may be temporarily absent from Malaysia.
3. Temporary absences from Malaysia are to be treated as forming part of the qualifying period provided that the individual must be in Malaysia immediately prior to and after that temporary absence.
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W