









1. In response to the Self-Employed Social Security Act 2017 (Act 789), the Government has gazetted three relevant subsidiary legislation on 21 September 2021, which will come into force on 1 October 2021.
2. Nowadays, even walking to deliver food is covered by SOCSO
3. In principle, the above subsidiary legislation will require
✅ Self-employed Service Providers Carrying and Delivering Goods and Food (“Relevant Persons”)
✅ be registered under the Self-Employed Social Security Act 2017
✅ and to make contributions
✅ so that if they suffer an accident (whether caused by a third party or not), they will be able to receive compensation.
4. The Amended of First Schedule Order, which also allows the Relevant Persons:
👉 to use “any other means of transport”, or
👉 not to use any motor vehicle or other means of transport to provide for the handling and delivery of goods or foodstuffs 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. 针对2017年自雇人士社会保险法令,政府已于2021年9月21日在宪报上颁布了三项相关附属法例,并将于2021年10月1日生效。
2. 如今,即使走路送餐,也在 SOCSO 保障范围内
3. 原则上,上述附属立法将要求:
✅ 提供货物或食品运输和交付服务的自雇人士(“相关人员”)
✅ 根据 2017年自雇人士社会保险法令进行登记,
✅ 并作出缴款,
✅ 这样,如果他遭受意外(无论是否由第三方造成),都将能够获得赔偿。
4. 修订后的指令,也允许相关人员:
👉 使用 “任何其他交通工具”,或
👉 不使用任何机动车或其他交通工具,提供货物或食品的搬运和交付

The service of carriage and delivery of goods or food by any person by means of any motor vehicle or any other conveyance owned by him, or managed, maintained or operated by that person, in any form of arrangement with the owner or lessor of the motor vehicle or other conveyance, or without using any motor vehicle or other conveyance; and whether for hire or reward or for any other valuable consideration or money’s worth or otherwise.


A qualifying company in the basis period for a year of assessment is exempted from the payment of income tax in respect of statutory income derived from a qualifying project, which is equivalent to the amount of allowance of fifty per cent (50%) of the qualifying capital expenditure incurred by that qualifying company.


1. 根据这项指令 [Income Tax (Exemption) (No. 10) Order 2021]:
👉 一家合格的公司 [qualifying company]
👉 在一个课税年度的基准期内 [basis period for a year of assessment],
👉 从一个合格的项目 [qualifying project] 中所获得的法定收入 [statutory income],
👉 相当于公司所产生的合格资本支出 [qualifying capital expenditure ] 的50%的津贴
👉 可以免征所得税。


A loan instrument or a financing arrangement pertaining to the restructuring or rescheduling of a loan or financing between a borrower or customer and a financial institution that is completed on or after July 1, 2021, but before December 31, 2021, is exempted from stamp duty.
1. 根据这项指令 [Stamp Duty (Exemption) (No. 11) Order 2021]:
👉 经申请,在2021年7月1日或之后,但在2021年12月31日之前完成的
👉 与贷款或融资重组或重新安排 [restructuring or rescheduling of a loan or financing ] 有关的贷款协议,
👉 可免征印花税。

Stamp duty is waived on a loan instrument or a financing agreement pertaining to a loan or financing facility made between a small and medium enterprise and a financial institution.


1. 根据这项指令 [Stamp Duty (Exemption) (No. 10) Order 2021]: 👉 在马来西亚国家银行中小企业基金下批准的贷款或融资机制 👉 中小企业与金融机构之间针对(2)的贷款或融资机制 👉 可免征印花税
2. 贷款配套 [loan or financing facility]:
✅ 所有经济部门配套 [All Economic Sectors Facility]
✅ 中小型企业自动化和数字化配套 [Small Medium Enterprises Automation and Digitalization Facility];或
✅ 农业食品配套 [Agrofood Facility]

Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium Enterprise
P.U. (A) 354 (2021) – Income Tax (Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium Enterprise) Rules 2021 – 8 September 2021

Special Deduction for Reduction of Rental to a Small and Medium Enterprise
P.U. (A) 353 (2021)- Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021 – 8 September 2021


1. 根据这项细则 [Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021]: 👉 2020年4月起至2021年12月这段期间;
👉 产业业者根据现有租约 [Tenancy Agreement],提供不少于30%的租金回扣给中小企业,
👉 将享有特别扣税 [Special Deduction] 2. 在根据该法第4(a)或(d)款确定房东在一个评估年度的基础期的租金收入调整后的收入时,应允许扣除相当于根据现有租赁协议减少的租金总额,即不低于月租金率的30%。 3. 产业业者 [Landlord] 需保留以下文件或资料: ✅ 一份根据1949年《印花税法令》盖章的租赁协议 [Tenancy Agreement];
✅ 针对符合资格的月份,另外一份单独的租金收入报表;
✅ 确认书 [confirmation letter]:
🅰️ 产业业者 [Landlord] 出具的确认书,确认减免租金的数额;以及
🅱️ 中小型企业出具的确认书,去确认收到租金减免;以及
✅ 中小企业公司的资格证明 – 由马来西亚中小型企业公司 [SME Corp. Malaysia ] 所发出的中小型企业地位的确认证件。


The Minister exempts a qualifying person from the payment of income tax in a basis period for a year of assessment in respect of the statutory income derived from a qualifying activity.
P.U. (A) 344 (2021)- Stamp Duty (Exemption) (No. 9) Order 2021 – 23 August 2021
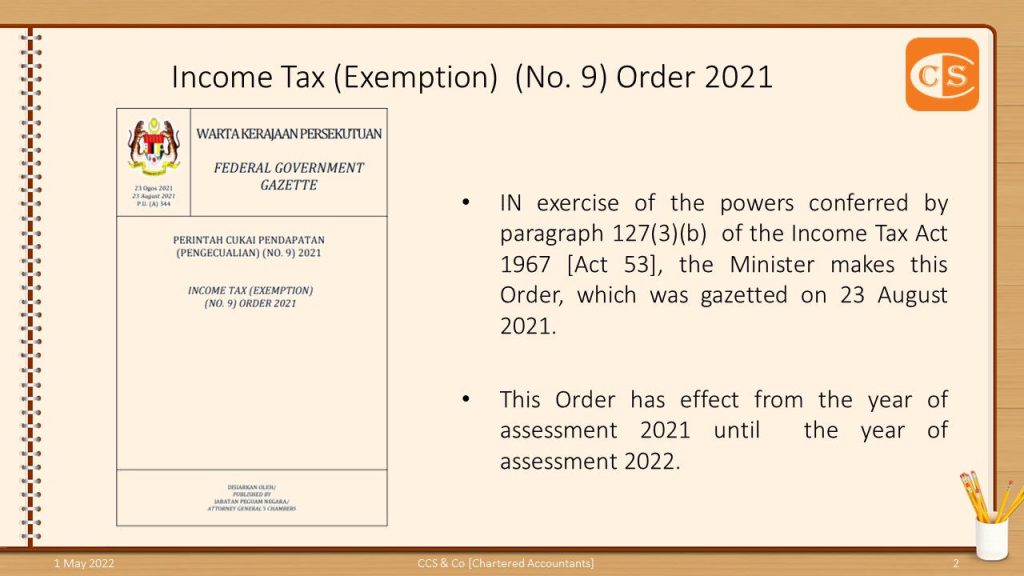
1. Under this Exemption Order:-
👉 Tourism companies that provide domestic travel packages for local or foreign tourists, including transportation by air, land or sea and accommodation
👉 Tax-exempt in respect of the statutory income derived from a qualifying activity
2. Conditions:-
👉 the total number of local tourists participating in a qualifying activity is at least 200
👉 Authorized person of the Ministry of Tourism, Arts and Culture of Malaysia must verify, in writing, the total number of local and foreign tourists involved in domestic tourism.
3. Where a qualifying person carries on a qualifying activity and an activity other than a qualifying activity, each activity shall be treated as a separate and distinct source of that qualifying person
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. 根据这项豁免指令 [Income Tax (Exemption) (No. 9) Order 2021]:
👉 为本地或外国游客提供国内旅游配套[包括:交通和住宿的旅游业公司
👉 在符合条件后,享有免税资格
2. 条件:
👉 本地游客游客总数不低于200人
👉 马来西亚旅游、艺术和文化部授权人必须以书面形式,核实参与国内旅游的本地和外国游客总数。
3. 符合条件的旅游公司,如果同时从事符合条件和不符合条件的旅游服务,每项服务应被视为单一及独立的收入来源 [separate and distinct source ]。

An instrument of loan or a financing agreement relating to the loan or financing facility executed between a small and medium enterprises and a financial institution is, on application, exempted from stamp duty.
P.U. (A) 333 (2021)- Stamp Duty (Exemption) (No. 8) Order 2021 – 12 August 2021


1. Under this Exemption Order:-
👉 Instrument between SMEs and financial institutions in connection with the Disaster Relief Facility 2021
👉 which is signed and executed from February 2 to December 31, 2021.
👉 is Exempted from stamp duty upon application.
2. Note that it is necessary to make an application 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼 1. 根据这项豁免指令 [Stamp Duty (Exemption) (No. 8) Order 2021]:
👉 在“2021年灾难救济基金(Disaster Relief Facility 2021)计划下
👉 中小企业与金融机构之间签署的与贷款或融资有关的合同,
👉 在2021年2月2日至12月31日这段时间所签署与执行的贷款或融资合同;
👉 经申请可免征印花税。
2. 注意,是需要做出申请的


