Day: June 1, 2021
-

TP FAQs 6: How the information in Form C differs from the contemporaneous TP Documentation
The DGIR is granted vast powers by Sections extensive Act to gather returns and information.
A taxpayer actively involved in employment, business, profession, or vocation must fill out the appropriate return form and include all the particulars mentioned.
These are the primary types:
- Form B (CP 4A) and Form BE (CP 4B) for individuals
- Form C (CP 5) for companies
- Form P (CP 3) for partnerships
- Form M (CP 54) for non-resident individuals, and
- Form T (CP 2) for trusts, estates, clubs, associations, societies, etc.
Hence, Form C is:
- a statement under section 77A of the Income Tax Act 1967 (ITA 1967);
- an income tax computation under subsection 77A(3) of ITA 1967; and
- a deemed notice of assessment under subsection 90(2) of ITA 1967.
Form C for YA 2022 consists of the followings:
- Basic particulars
- Part A: statutory income, total income and chargeable income
- Part B: tax payable/repayable and status of tax
- Part C: capital allowances and charges under schedule 3, reinvestment allowance under schedule 7A and investment allowance for the service sector under schedule 7B
- Part D: incentive claim
- Part E: claim for losses
- Part F: particulars of company
- Part G: other particulars
- Part H: particulars of auditor
- Part J: particulars of the tax agent and signature of the person who completes this return form
- Declaration
If you look closely, you will notice that the taxpayer is responsible for filling out most of the information on Form C. Some of the fields demand numerical data, while others require information that is pertinent to the situation.
The taxpayer must also provide a yes or no response to some of these questions, for example, F8 under Part F, whereby the taxpayer is being asked whether he carries out controlled transactions under sections 139 and 140A or not.

Enter the number ‘2’ in the space provided for ‘No’ if there are no controlled transactions or if the question does not apply, and then move on to the next question.
However, if the answer is affirmative (if the company carries out controlled transactions), the taxpayer must further fill in other information as required in the appendix.
-
TP FAQs 5: Guide on How to Prepare a Limited Transfer Pricing Document
Who should prepare Transfer Pricing Documentation?
The Transfer Price Guidelines 2012 provide additional clarification that the requirements for the preparation of contemporaneous transfer pricing documentation that the TP Rules mandate would be limited to the following:
- for a person carrying on a business, where the gross income exceeds RM25 million, and the total amount of related party transactions exceeds RM15 million; or
- in relation to financial assistance, where such financial assistance exceeds RM50 million (the Guidelines do not apply to transactions involving financial institutions).
Any person who falls outside the scope above
- may opt to fully apply all relevant guidance as well as fulfil all Transfer Pricing Documentation requirements in the Guidelines; or
- alternatively may opt to comply with TP Documentation requirements under paragraphs 25.4(a), (d) and (e) only:-
- organisational structure;
- Controlled transactions; and
- Pricing policies.
In this regard, the person can apply any method other than the five described in the Guidelines, provided it results in or best approximates arm’s length outcomes.
Guide on How to prepare a Simple Limited Transfer Pricing Document
Today we’ll look at how to prepare a simplified or limited transfer pricing document.
You are the accountant of Ever Bright Sdn. Bhd. and the Group CFO has asked you to prepare a transfer pricing document for the company.
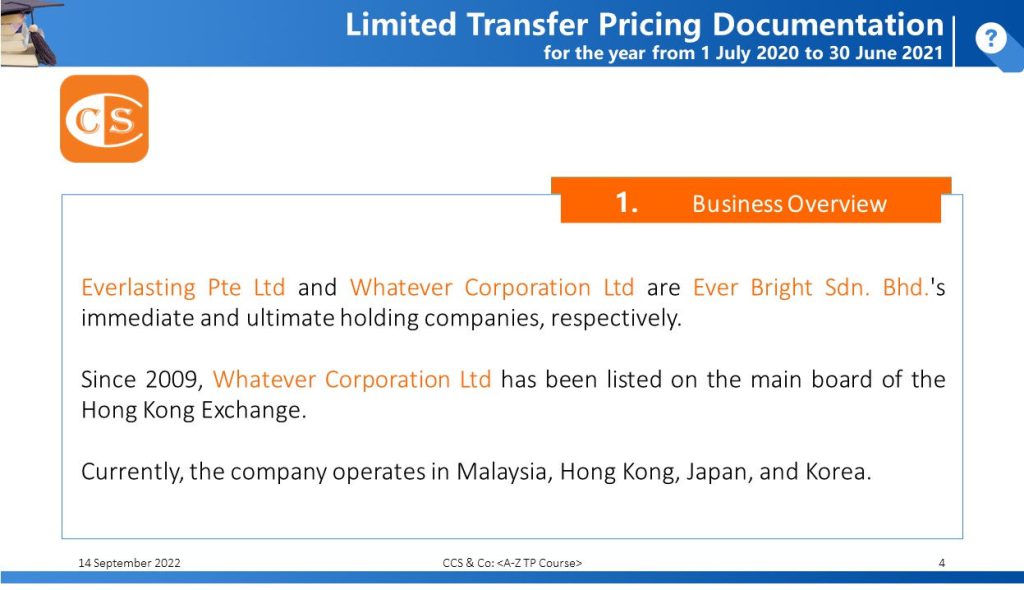
You understand that this group comprises three companies, i.e. Ever Bright Sdn. Bhd., Everlasting Pte Ltd and Whatever Corporation Ltd.
Step 1:
You first need to determine whether the relationship between the three companies is an associated company under s 140A of the Income Tax Act 1967 or not.
You find that Whatever Corporation Ltd has the power to appoint one or more directors or BODs in Everlasting Pte Ltd and Ever Bright Sdn. Bhd.
Whatever Corporation Ltd also directs Everlasting Pte Ltd to buy finished goods from Ever Bright Sdn. Bhd.
Therefore you conclude that they are associated persons.
Step 2:
You are going to need to recognise several terms right now:
Transfer price is the price at which related parties transact with each other,
Transactions between related parties (more specifically known as associated persons) are referred to as “controlled” transactions“, as distinct from “uncontrolled” transactions between independent companies.
According to the arm’s length principle, a transfer price is acceptable if all transactions between associated parties are conducted at the arm’s length price. Arm’s length price is the price which would have been determined if such transactions were made between independent entities under the same or similar circumstances.
Step 3:
Next, you need to determine whether you need to prepare a detailed transfer pricing document as required by Rule 4(2) of the Income Tax (Transfer Pricing) Rules 2012 or whether you can choose to prepare a simplified version of the transfer pricing document as provided by the Transfer Pricing Guidelines 2012.
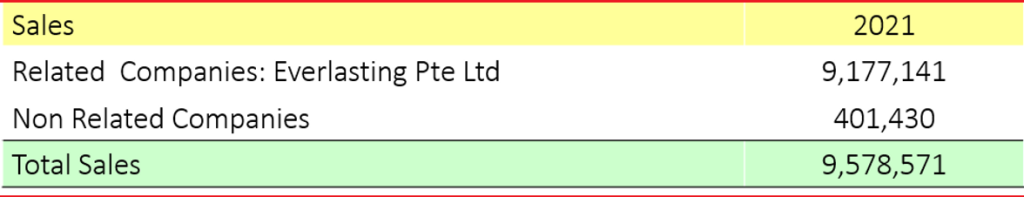
As a result of your inquiry, you discover the sale of Ever Bright Sdn. Bhd. is RM9,578,571, and the transaction with a related party is RM9,177,141; consequently, following the transfer pricing guidelines, you have the option of preparing a simplified version of the transfer pricing document.
Step 4: Get Ready
What you need to prepare are:-
- Organisational Structure;
- Controlled Transactions; and
- Pricing Policies.
1. Organisational Structure
It would help if you described Ever Bright Sdn. Bhd.’s worldwide organisational and ownership structure (including a global organisation chart and any substantial changes to the relationship, if any), covering all associated persons whose transactions directly or indirectly affect the pricing of the documented transactions.
It would help if you also described Ever Bright Sdn. Bhd.’s Company organisation chart.

Even though a product description does not need to be included in the simplified transfer pricing documentation for it to be legitimate, a description of the product can make it much simpler for an Inland Revenue officer to comprehend what the company is selling.



2. Controlled Transactions
- Description of details of the property or services to which the international/domestic transaction relates; any intangible rights or property attached to it, the participants, the scope, timing, frequency, type and value of the controlled transactions (including all relevant related party dealings in relevant geographic markets);
- Names and addresses of all associated persons, with details of the relationship with each such associated person;
- The nature, terms (including prices) and conditions of international transactions (where applicable) entered into with each associated person and the quantum and value of each transaction;
- An overview description of the business, as well as a functional analysis of all associated persons with whom the taxpayer has transacted;
- All commercial agreements setting forth the terms and conditions of transactions with associated persons as well as with third parties;
- A record of any forecasts, budgets or other financial estimates prepared by the person for the business and each division or product separately.


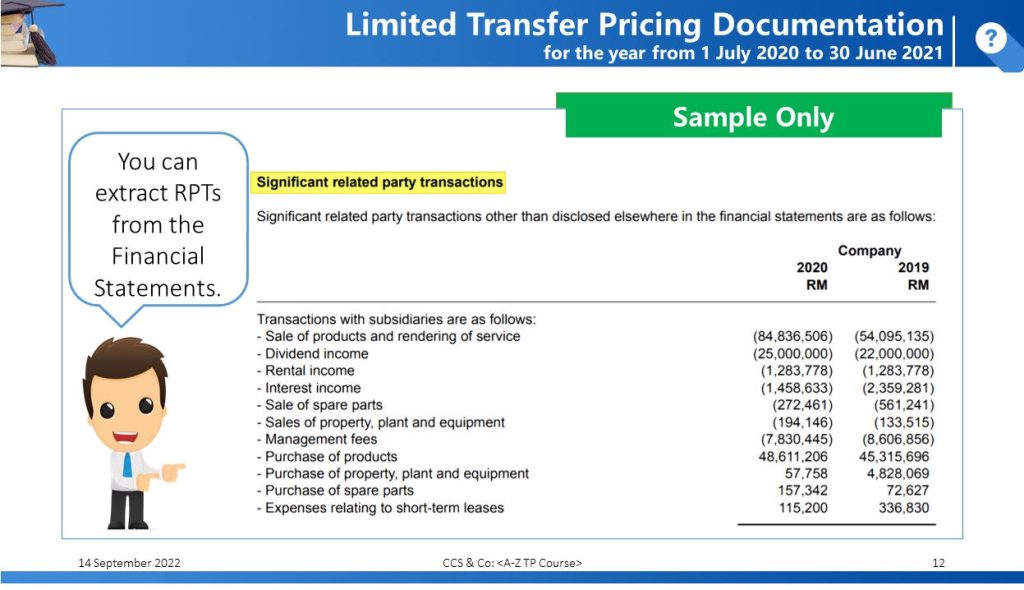
This diagram is only provided for illustrative purposes and has absolutely nothing to do with the scenario that was just presented. FAR Analysis
Functions performed
Ever Bright Sdn. Bhd. supplying the manufacturing services provides the plant, machinery and labour necessary to manufacture the relevant product. Everlasting Pte Ltd (the ‘principal’) supplies the relevant raw materials and owns all the intellectual property relating to the products, such as patents and trademarks.
Under the tolling arrangement between Ever Bright Sdn. Bhd. and Everlasting Pte Ltd, raw materials for manufacturing are entirely consigned by Everlasting Pte Ltd and Ever Bright Sdn. Bhd. does not own these raw materials.
The manufacturing team of Ever Bright Sdn. Bhd. is mainly engaged in the following key activities:
- Particleboard, Furniture, and value-added wood-based products manufacturing,
- Production Planning,
- Quality Control,
- Packaging and Logistics,
- Technical Services,
- Environmental, Health and Safety
- HR and IT
- Finance
Assets employed
Ever Bright Sdn. Bhd. own assets: factory buildings, plant and machinery, furniture and fixtures, office equipment and motor vehicles.
Everlasting Pte Ltd holds all the material intellectual property rights. Accordingly, as a toll manufacturer, Ever Bright Sdn. Bhd. does not own any significant intangible assets.
No Risk, No Reward: The Risks Assumed
Ever Bright Sdn. Bhd. is not responsible for any risks caused by macroeconomic variables such as economic downturns or conditions peculiar to a particular sector. The responsibility for this risk lies with Ever Bright Sdn. Bhd.
However, if there were a fall in customer demand, Everlasting Pte Ltd would have a comparable decrease in the number of orders it processed. The possibility exists that Ever Bright Sdn. Bhd. will not fully recover its operational costs due to insufficient sales volumes.
As a result, it can be deduced that Ever Bright Sdn. Bhd. is exposed to some degree of indirect industry and market risk; nevertheless, the impact has not been particularly noteworthy during the time under consideration.
Only Everlasting Pte Ltd supplies Ever Bright Sdn. Bhd. with the raw materials used in the manufacturing processes carried out by Ever Bright Sdn. Bhd.
As a consequence of this, Ever Bright Sdn. Bhd. does not have legal ownership of these raw materials.
Any costs associated with product liability suits will, in the end, be shouldered by Everlasting Pte Ltd as principal. As a result, Ever Bright Sdn. Bhd. is not responsible for the risks associated with product responsibility and warranty.
Everlasting Pte Ltd will bear the risks associated with holding raw materials and finished goods inventory, as well as final demand and price risks.
The production risk that is connected with Ever Bright Sdn. Bhd.’s ordinary manufacturing operations are borne by the company.
The Technical Services section of Ever Bright Sdn. Bhd. manages the company’s production risk through the implementation of continuous process improvement.
Ever Bright Sdn. Bhd. sell all its finished goods to Everlasting Pte Ltd, who are unlikely to default on payment, or delay payment, hence Ever Bright Sdn. Bhd. does not bear credit and collection risk.
Ever Bright Sdn. Bhd. mainly transacts in MYR,
Functional Characterisation of Ever Bright Sdn. Bhd.
The above analysis of the functions performed includes risk assumed and assets employed by Ever Bright Sdn. Bhd. and its related party, Ever Bright Sdn. Bhd. may be characterised as a toll manufacturer in the industry.
3. Pricing Policies – Paving the way for the journey ahead
The formulation of transfer pricing policies is essential to implementing transfer pricing.
The company should have a transfer pricing policy to help ensure that all of its employees are on the same page.
It is an undeniable indication that transfer pricing has been given due consideration and that it has been carried out appropriately.
It is common knowledge that a transfer pricing policy should be carefully crafted and methodically carried out because of the long-term nature of the situation.
Your company can choose from various pricing methods; however, broadly speaking, three primary pricing techniques are the most frequently used by businesses when setting their prices:-
- Cost Plus Pricing
- Competitive Based Pricing
- Value-Based Pricing
The pricing method known as “cost-plus” involves “marking up” (adding a fixed percentage) the price of the goods and services to arrive at the final selling price.
You, as the seller, would first perform a calculation considering the fixed and variable costs incurred in the production of your goods. Then you would apply the markup % to the total amount calculated.
This tactic is often utilised since it is straightforward to justify and is typically fair and non-discriminatory.
Pros:
- Less likelihood of price wars
- It can guarantee certain levels of earnings.
- Simple to implement
Cons:
- Reduces productivity and raises costs without providing any benefits.
- It is not guaranteed to pay all costs because a significant portion of the computation is based on estimations.
- When necessary, it cannot be easy to make pricing adjustments.
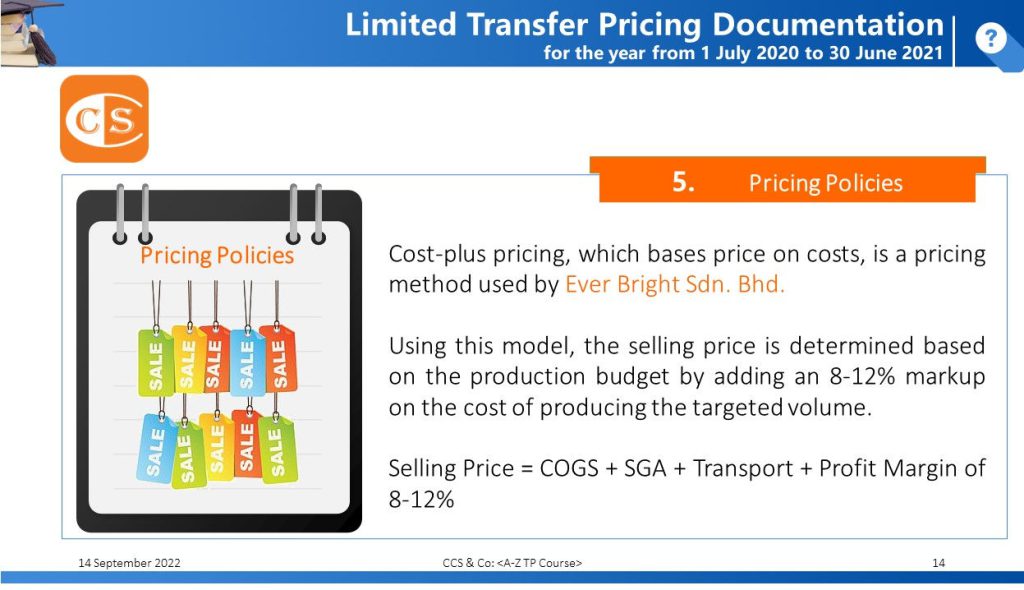
You have observed that the management of Ever Bright Sdn. Bhd. has adopted the cost-plus pricing approach; hence, you need to produce a description and show how the method functions.
You notice that Ever Bright Sdn. Bhd.’s management is adopting the Cost-plus pricing method; therefore, you need to describe and illustrate how it works.
Process costing is a method in which raw materials, labour, and factory overhead are charged to the main cost or department.
The costs charged to each product unit are determined by dividing the total costs charged by the main cost by the number of units produced at the main cost.
In the process costing calculation, in general, there are three required data;
- production data,
- overhead cost, and
- raw material cost.
Cost of goods sold per unit is calculated as:
- Cost of goods sold per unit = Total Cost / Equivalent Unit


With these steps, that’s it, you’ve completed a simplified version of your transfer pricing document. Congratulations!
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
要获得即时更新,请与我们保持联系
1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍
- https://www.facebook.com/YourHRAdvisory/?ref=pages_you_manage
- https://www.facebook.com/YourAuditor/?ref=pages_you_manage
4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy
6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
-

TP FAQs 4: What Needs To Be Included in a Local File?
Income Tax (Transfer Pricing) Rules 2012
Under Rule 4(2) of the Income Tax (Transfer Pricing) Rules 2012, the contemporaneous transfer pricing documentation shall include records and documents that provide a description of the following matters:
- organisational structure, including an organisation chart covering persons involved in a controlled transaction;
- nature of the business or industry and market conditions;
- the controlled transaction;
- strategies, assumptions and information regarding factors that influenced the setting of any pricing policies;
- comparability, functional and risk analysis;
- selection of the transfer pricing method;
- application of the transfer pricing method;
- documents that provide the foundation for or otherwise support or were referred to in developing the transfer pricing analysis;
- index to documents; and
- any other information, data or document considered relevant by the person to determine an arm’s length price.
根据《2012 年所得税 (转让定价) 细则》第4(2)条],同期转让定价文档应包括提供以下事项的记录和文件:
- 组织结构,包括涉及受控交易人员的组织结构图。
- 业务或行业的性质和市场条件。
- 受控交易。
- 影响任何定价政策制定的战略、假设和因素的信息。
- 可比性、功能和风险分析。
- 转让定价方法的选择。
- 转让定价方法的应用。
- 为转让定价分析提供基础或以其他方式支持或在制定转让定价分析时参考的文件。
- 文件的索引;以及
- 该纳税人士认为与确定正常价格有关的任何其他信息、数据或文件。

In layman’s words, the Income Tax (Transfer Pricing) Rules 2012 mandate that Malaysian entities that conduct business with associated persons must compile contemporaneous Transfer Pricing documentation per the above requirements.
This applies to both cross-border as well as domestic transactions.
The Inland Revenue Board of Malaysia also published Malaysian Transfer Pricing Guidelines 2012 to explain the provision of Section 140A in the Income Tax Act 1967 and the Income Tax (Transfer Pricing) Rules 2012.
It governs the standard and rules based on the arm’s length principle to be applied to transactions between associated persons.
The Transfer Price Guidelines 2012 provide additional clarification that the requirements for the preparation of contemporaneous transfer pricing documentation that are mandated by the TP Rules would be limited to the following:
- for a person carrying on a business, where the gross income exceeds RM25 million, and the total amount of related party transactions exceeds RM15 million; or
- in relation to financial assistance, where such financial assistance exceeds RM50 million (the Guidelines do not apply to transactions involving financial institutions).
用通俗的话说,《2012 年所得税 (转让定价) 细则》规定,与关联人士开展业务的马来西亚实体,必须按照上述的要求准备同期转让定价文档。
这既适用于跨境交易,也适用于国内本土交易。
马来西亚内陆税收局还发布了《2012年马来西亚转让定价指南》,以解释《1967年所得税法》第140A条和《2012年所得税(转让定价)规则》中的规定。
针对关联人士之间的交易,它规范了独立交易原则适用的标准和规则。
《2012年转让价格指南》提供了补充说明,即《转让定价细则》所规定的编制同期转让定价文件的要求将限于以下的情况:
- 对于经营业务的人士,其总收入超过 2,500 万令吉,并且关联方交易总额超过 1,500 万令吉;或
- 就财政援助而言,该财政援助超过 5,000万令吉(该指南不适用于涉及金融机构的交易)。

Limited Transfer Pricing Documentation
Any person which falls outside the scope above:
- may opt to fully apply all relevant guidance as well as fulfil all Transfer Pricing Documentation requirements in the Guidelines; or
- alternatively may opt to comply with TP Documentation requirements under paragraphs 25.4(a), (d) and (e) only:-
- organisational structure;
- Controlled transactions; and
- Pricing policies.
In this regard, the person can apply any method other than the five described in the Guidelines, provided it results in or best approximates arm’s length outcomes.

任何不属于上述范围的人士:
- 可以选择完全采用相关指南,并满足《指南》中所有转让定价文件的要求;或
- 可以选择只遵守第25.4(a)、(d)和(e)段的转让定价文件的要求,即只准备:
- 组织结构。
- 受控交易;以及
- 定价政策。
在这方面,纳税人士可以采用《指南》中描述的五种方法之外的任何其他方法,只要其结果是或最接近公平交易的价格。

Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
要获得即时更新,请与我们保持联系
1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍
- https://www.facebook.com/YourHRAdvisory/?ref=pages_you_manage
- https://www.facebook.com/YourAuditor/?ref=pages_you_manage
4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy
6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
-
TP FAQs 3: What Needs To Be Included in a Master File?
The Master File is intended to provide tax administrations with an overview of the economic, legal, financial and tax arrangements within an MNE.
Simply put, it is a 360-degree look at the company’s global transfer pricing operations and policy.
The information required is divided into five categories:
1. MNE’s Organisational Chart
- A diagram depicting the legal and ownership structure of the MNE, as well as the geographical location of its functioning businesses.
2. A general description of the MNEs’ Business (es)
- Important drivers of business profit
- A description of the supply chain for the group’s 5 most significant products and/or service offerings by turnover plus any other products and/or services amounting to more than 5% of group income;
- A list and a brief description of essential service arrangements between members of the MNE group, other than research and development (R&D) services;
- A description of the main geographic markets
- A functional analysis that outlines the primary contributions to value creation made by individual entities that are part of the group, such as the main functions that are carried out, the essential risks that are assumed, and the important assets that are utilised;
- A description of important business restructuring transactions, acquisitions and divestitures
3. MNE’s Intangibles Assets
- Notable intangible assets or categories of intangible assets, and which organisations are their owners;
- General description of the MNEs’ overall strategy for the development, ownership and exploitation of intangibles, group’s transfer pricing policies related to R&D and intangibles etc.
4. MNE’s Intercompany Financial Transactions
- Intra-Group financing arrangements and major financing arrangements with unrelated parties
- A general description of how the group is financed, including important financing arrangements with unrelated lenders
5. MNE’s Financial and Tax Position
- A list and a brief description of the MNE group’s existing unilateral advance pricing agreements (APAs) and other tax rulings relating to the allocation of income among countries
主体文档旨在为税务管理部门提供一个跨国企业内部的经济、法律、财务和税收概览。
简单地说,它是对公司的全球转让定价业务和政策的360度观察。
所需信息分为五类:
1. 组织架构
- 集团的全球组织架构和所有成员实体的地理分布
2. 业务描述
- 净利的主导因素
- 利润的重要价值贡献因素,营业收入位居前 5 位以及占营业收入总额超过 5% 的集团产品或者劳务
- 集团内除研发以外的重要关联劳务安排,集团内各成员实体在价值创造方面的主要贡献
- 集团产品和服务的主要地理市场的描述
- 功能分析,按照履行的关键职能、承担的重要风险和使用的重要资产,描述对价值创造的主要贡献
- 集团发生的业务重组及变更
- 概述用于为本组织融资的许多方法,包括与非关联贷款人作出的重要融资安排。
3. 无形资产
- 集团无形资产开发、所有权归属和应用的整体战略描述
- 重要的无形资产及其所有权人,与无形资产相关的协议清单,研发和其他与无形资产相关的转让定价政策,集团重要无形资产相关权益的关联转让情况。
4. 融资安排
- 集团内融资安排以及与非关联方的主要融资安排
- 集团内提供集中融资功能的成员实体情况,集团内各关联方之间融资安排的总体转让定价政策。
5. 财务以及税务状况
- 集团最近一个会计年度的合并财务报表,集团内各成员实体签订的单边预约定价安排、双边预约定价安排等。
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
要获得即时更新,请与我们保持联系
1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍
- https://www.facebook.com/YourHRAdvisory/?ref=pages_you_manage
- https://www.facebook.com/YourAuditor/?ref=pages_you_manage
4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy
6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
-
TP FAQs 2: What is the purpose of Contemporaneous TP Documentation?
Photo: 張靜靜 For the Inland Revenue | 对内陆税收局而言
To obtain information on related party transactions and comparability information through Contemporaneous TP Documentation provided by the company:-
- To serve as a reference for the selection of investigation subjects
- To assess and check the possibility of tax irregularities in transfer pricing, to test whether the taxpayer has engaged in transfer pricing practices and as a preliminary basis for tax adjustments.
通过企业提供的转让定价同期资料,获取关联交易 [Related Party Transactions] 的信息及可比 [Comparability] 信息
- 作为选择调查对象的参考
- 评估和检查纳税人在转让定价中存在税务违规的可能性,检验纳税人是否存在转让定价行为并可作为是否应进行纳税调整的初步依据。
For The Taxpayers | 对纳税人而言
Meeting compliance requirements (for those businesses that meet the threshold for the preparation of Contemporaneous Transfer Pricing Documentation)
- Avoid penalties for failure to prepare Contemporaneous Transfer Pricing Documentation under section 113B of the Income Tax Act 1967
- [Penalty: from a minimum of not less than RM20,000 to a maximum of RM100,000]
- This will demonstrate a willingness to develop and implement transfer pricing that is consistent with the principle of independent trading and ensure that its transfer pricing is tested, particularly those taxpayers that have been making marginal profits and losses [even though without a profit, but continue to operate anyway] or are suspected of transfer pricing avoidance.
- Internal business management needs, including group restructuring, assessment of the performance of entities within the group 】
满足合规性要求 (对于那些达到需要准备转让定价同期资料门槛的企业)
- 避开1967年所得税法令第113B条文下,没有准备转让定同期资料的罚款
- [罚款额:从最低不少于20千令吉,到最高不超过100千令吉]
- 可以显示其制定和执行符合独立交易原则的转让定价的意愿,确保其转让定价是经得起检验的,也规范了纳税人税务行为及实务操作,特别是那些常年微利 [赚很少]、亏损 [没有赚过钱,但是还是继续营业] 或有转让定价避税嫌疑的企业
- 企业内部经营管理需要,包括:集团结构重组、集团内各实体业绩评估
Best Practices For Contemporaneous Documentation | 同期文档的最佳实践
1. Get familiar with the Transfer Pricing Regulations
Tax law can be difficult to understand, particularly when comparing the laws of different jurisdictions.
The rules that govern transfer pricing are known to undergo periodic revisions in the modern era.
For instance, new rules were implemented not too long ago in Malaysia, and they came into operation effectively from January 1, 2021.
It is essential to maintain a current knowledge base on the timing of the submission of documentation (Currently, in Malaysia, all documentation should be made available within 14 days upon request by IRB) and the question of whether or not countries have made particular changes to their policy.
熟悉转让定价条例
Photo: 葉峻豪 税法可能很难理解,特别是在比较不同司法管辖区的法律时。
众所周知,在现代社会,管理转让定价的细则会定期进行修订。
例如,不久前马来西亚就实施了新的规则,并从2021年1月1日开始有效实施。
在提交文档的时间点(目前,在马来西亚,所有的文档应需要在内陆税收局要求的14天内提供),以及各国是否对其政策进行了特别修改的等方面,与时并进是非常重要的。
2. Review your Documentation each year
It is a smart practice to examine and update all relevant documents annually. This will help to guarantee that your business does not incur any fines as a result of inaccurate documentation.
These mistakes arise when businesses prepare their documentation for the year but then neglect to keep it updated as the year progresses.
每年审查你的文件
每年检查和更新所有相关文件是一个明智的做法,这将有助于保证你的企业不会因为不准确的文件而招致任何罚款。
当企业准备好当年的文件,但随着时间的推移却忽略了保持更新,就会出现这类错误。
3. Keep up with the legal contracts between Companies
Making sure that your Intra-Group Legal Agreements are up to date will guarantee that the audit goes as smoothly as possible.
掌握公司之间的法律合同
确保你的集团内部的法律协议是最新的,将保证审计尽可能地顺利进行。
4. Be consistent with your Customs and Duty Declarations
It is of the utmost importance to guarantee that your in-house customs department operates effectively to guarantee that all international transactions are free of errors and contain information that is consistent throughout.
要与你的海关和关税申报保持一致
最重要的是保证你的内部海关部门的有效运作,以保证所有的国际交易精准无误,同时也包含贯穿始终的信息。
5. Maintain a dependable Point of Contact at all times
The point of Contact is the person who represents an organisation for a specific task.
It’s possible for there to be inconsistencies in your documentation if you prepare it utilising numerous tax or legal consultants located in different countries.
To ensure that your documentation is correct everywhere it is used, you should make every effort to keep a single point of contact centralised inside your firm and with the service provider you use.
始终确保有一个可靠的联络人
联系点是代表在一个组织内,授予完成特定任务的人。
如果你利用位于不同国家的许多税务或法律顾问来准备文件,就有可能出现不一致的情况。
为了确保你的文件在任何地方都是正确的,你应该尽一切努力在你的公司内部和你使用的服务提供商之间保持一个单一的联系点。
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
要获得即时更新,请与我们保持联系
1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍
- https://www.facebook.com/YourHRAdvisory/?ref=pages_you_manage
- https://www.facebook.com/YourAuditor/?ref=pages_you_manage
4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy
6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/